Most people have no idea what goes into
a major property loss claim until they're
standing in the middle of one.
This is how Michigan Fire Claims makes sure nothing falls through the cracks, and everything you're entitled to is on the table.
Tell Us About Your Loss — We'll Take It From Here
Phase One: Emergency
Response
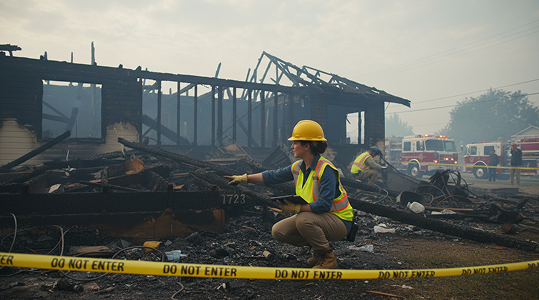
The first 24 to 48 hours after a major loss are critical. Michigan Fire Claims wastes no time and mobilizes immediately. From on-site inspection and policy analysis to emergency advance requests, everything that needs to happen in those first hours gets handled professionally, so you're never making high-stakes decisions alone and under pressure.
What Happens in Phase One
Site inspection and damage assessment — Our team walks the property and begins a detailed evaluation of all losses, visible and non-obvious.
Policy review and coverage analysis — We read your policy the way an advocate reads it, not the way an insurer wants you to read it.
Claim reporting to your insurance carrier — We handle the first communication with your insurer, setting the right tone from the start.
Emergency advance requests — When immediate financial relief is available under your policy, we pursue it without delay.
Recovery planning — Before anything else moves forward, you understand exactly where you stand and what the path forward looks like.
Phase Two: Documentation,
Estimation, and
Preparation
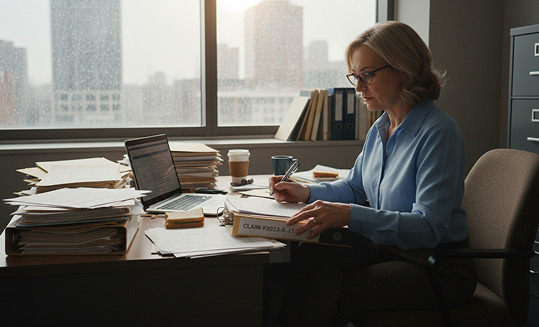
Claim preparation is where most unrepresented policyholders quietly lose money, and never know it. Our team of building estimators, contents specialists, and licensed public adjusters handles every aspect of your claim professionally, thoroughly, and on your behalf, so nothing gets missed and nothing gets submitted without your approval.
What Happens in Phase Two
Building damage estimating — Our estimators assess structural damage and prepare real-world replacement cost figures, not whatever the insurance company’s preferred contractor submits.
Contents documentation and valuation — Every item of value in your home or business is inventoried and substantiated, so nothing gets written off as negligible.
Meetings with insurance representatives — We attend and handle all communications with the carrier’s team on your behalf.
Business interruption claims — If your business was affected, lost income and operational disruption are documented and submitted as part of the full claim.
Claim review with the insured — Before anything is submitted, you see it. You understand it. You approve it.
Phase Three: Settlement,
Recovery, and
Getting You Paid
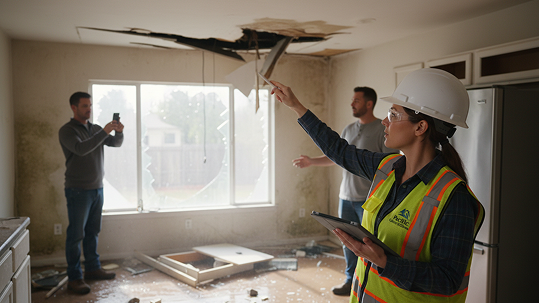
Submitting a claim and getting paid are two very different things, and Phase 3 is where our advocacy is most visible. We submit your fully documented claim, manage every interaction with the carrier through to final payment, and meet every delay tactic or lowball response with a professional, prepared counterpart on your side.
What Happens in Phase Three
Documented claim submission — The complete, prepared claim is presented to the insurance carrier with full supporting documentation.
Active negotiation — Our licensed public adjusters negotiate directly with the insurer’s adjusters, challenging low offers and pushing for the maximum your policy supports.
Consistent client communication — You’re kept informed throughout. No black holes, no waiting weeks for an update.
Settlement document management — All closing documents are reviewed and prepared by our team before any signatures are required.
Final payment coordination — We see the process through to the point where the funds are in your hands.
This Is Why People Who Don't Call Us First Often Wish They Had
The adjuster evaluating your claim is employed by the same company that issued your policy. They're trained, experienced, and working within a system built to protect the insurer's interests. There's nothing underhanded about it. It's simply the structure you're navigating alone when you don't have professional representation. Coverage gets overlooked. Damages go undocumented. Claims drag. Policyholders who call Michigan Fire Claims immediately after a loss consistently resolve faster and recover more, because a prepared, experienced team changes the dynamic entirely.
-

Thank you for the work performed on our fire claim. We are happy with the settlement. We will continue to refer you to friends, relatives, and any one we meet with a fire loss.
John Vandoer
-
Michigan Fire Claims, Inc was able to do everything they assured me could be done on the loss. We were able to take the settlement, pay off the home and purchase a beautiful home not far from work.
Brett and Cindy Deguise
-
We were so happy to have had you recommended to us by a friend who had also experienced a fire. Nik met with us and took the time to explain our policy and the entire claim process. He helped us avoid numerous mistakes that could have been made. Michigan Fire Claims, Inc performance was simply fabulous.
Steve and Bonnie Dexter
-
We wish to thank you for handling our flood with professionalism and care to our home and belongings. Michigan Fire Claims, Inc was able to get us double the offer from the insurance company. Thank you!
Vargel Fili